
Previsioni di volatilità settimanale su S&P 500
Il Gandalf Volatility Forecaster segnala una netta riaccelerazione della volatilità prevista. Sui 99 titoli presenti in entrambe le rilevazioni, la quota nelle classi 3–4 sale dal 49,5% al 67,7%, invertendo la normalizzazione osservata nella settimana precedente.
L’analisi rappresenta un’estrazione dei 100 titoli a maggiore capitalizzazione dell’S&P 500. I risultati descrivono questo campione selezionato e non la totalità dei componenti dell’indice.
Il modello assegna a ciascun titolo la classe di volatilità più probabile su una scala da 0 a 4: molto bassa, bassa, normale, alta e molto alta. La percentuale nelle heatmap misura la confidenza relativa della classificazione scelta, non la probabilità di rialzo o ribasso del prezzo.
Contesto generale: ritorno a un regime più teso
Sull’intero paniere di 100 titoli, le classi 3–4 passano complessivamente da 49 a 68 componenti. La classe 3 sale da 27 a 41 titoli e la classe 4 da 22 a 27. All’estremo opposto, la classe 0 si riduce da 12 a un solo titolo; la classe 1 scende da 27 a 21 e la classe 2 da 12 a 10.
Il cambiamento non riguarda quindi soltanto pochi casi estremi: la distribuzione si sposta nel suo insieme verso le fasce superiori. Nel campione comparabile si registrano 19 ingressi nelle classi 3–4 e una sola uscita, segnalando un aumento ampio della pressione prevista.
| Classe | Definizione | 16 agosto | 23 agosto |
|---|---|---|---|
| 0 | Molto bassa | 12% | 1% |
| 1 | Bassa | 27% | 21% |
| 2 | Normale | 12% | 10% |
| 3 | Alta | 27% | 41% |
| 4 | Molto alta | 22% | 27% |
Distribuzione dei titoli per classe
L’istogramma rende visibile lo spostamento dalle classi 0–2 verso le classi 3–4. Arancione indica la rilevazione precedente; verde quella corrente.
Molto bassa
Bassa
Normale
Alta
Molto alta
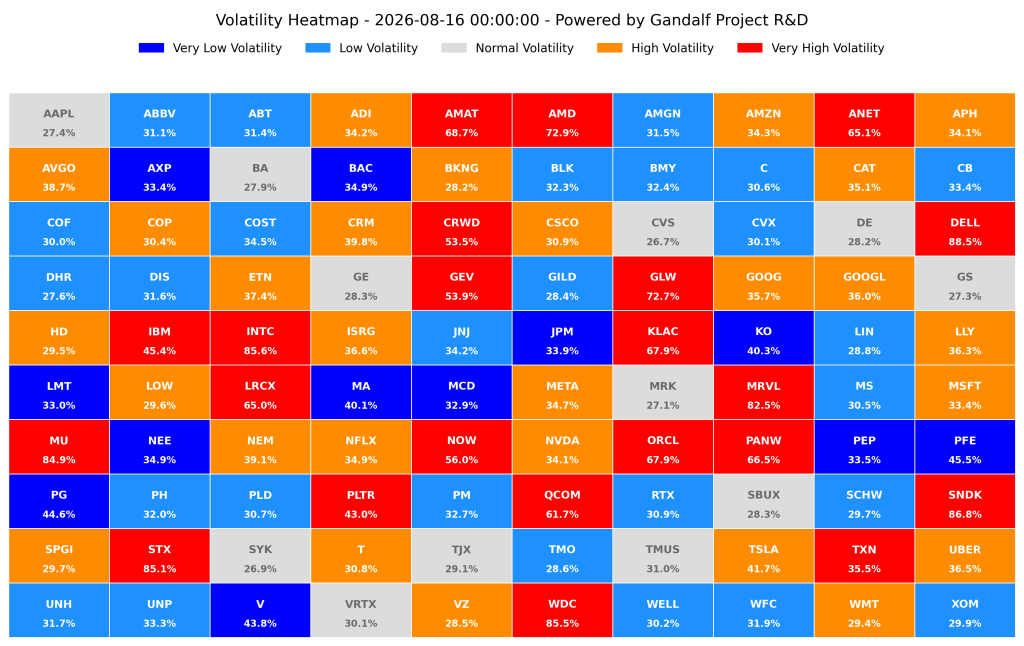
Previsione elaborata il 16 agosto 2026.
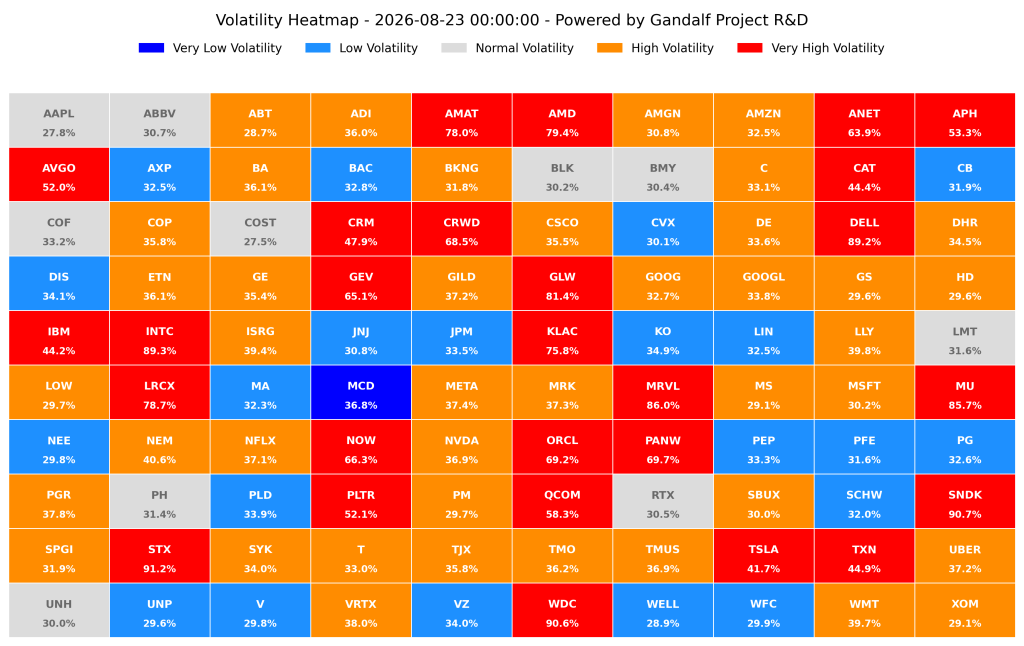
Previsione elaborata il 23 agosto 2026.
Dinamiche settoriali
Health Care: il principale motore della riaccelerazione
Nel paniere analizzato, l’Health Care comprende 15 titoli comparabili e registra il cambio più marcato. La classe media sale da 1,40 a 2,53 e la quota nelle classi 3–4 dal 13,3% al 66,7%. Thermo Fisher Scientific, Gilead, Amgen, Danaher e Abbott passano dalla classe 1 alla 3; MRK, Vertex e Stryker entrano nella fascia alta con movimenti di una classe. Il settore torna così da un profilo prevalentemente basso a una configurazione molto più esposta.
Industrials e Financials: pressione in aumento
Tra gli 11 Industriali comparabili, la quota nelle classi 3–4 sale dal 36,4% al 63,6% e la classe media da 2,00 a 2,73. Boeing, GE e Deere entrano in classe 3, mentre Lockheed Martin passa dalla classe 0 alla 2. GEV e GLW restano in classe 4.
Nei Financials, 14 titoli comparabili, la quota nelle fasce alte aumenta dal 7,1% al 28,6%. Citigroup e Morgan Stanley passano dalla classe 1 alla 3; Goldman Sachs sale dalla 2 alla 3. La classe media settoriale cresce da 0,86 a 1,71.
Consumer Staples ed Energy: recupero delle classi elevate
Nei Consumer Staples, sei titoli, la classe media sale da 0,83 a 1,83. Philip Morris passa dalla classe 1 alla 3, mentre la quota settoriale nelle classi alte raddoppia dal 16,7% al 33,3%. Nell’Energy, tre titoli, la quota nelle classi 3–4 passa dal 33,3% al 66,7%, con Exxon Mobil che sale dalla classe 1 alla 3.
Tecnologia: volatilità elevata persistente e in lieve rafforzamento
L’Information Technology mantiene il profilo più teso. Tra 29 titoli comparabili, il 96,6% resta nelle classi 3–4 e la classe media sale da 3,69 a 3,79. AMAT, AMD, ANET, APH, AVGO, CRM, CRWD, DELL, GLW, IBM, INTC, KLAC, LRCX, MRVL, MU, NOW, ORCL, PANW, QCOM, SNDK, STX, TXN e WDC concentrano segnali molto elevati.
Consumer Discretionary più teso; Communication Services stabile
Nel Consumer Discretionary, otto titoli comparabili, la quota nelle classi 3–4 sale dal 62,5% all’87,5%, sostenuta dagli ingressi di TJX e Starbucks. Nei Communication Services la quota resta al 75,0%: Verizon scende dalla classe 3 alla 1, mentre T-Mobile entra in classe 3.
Le variazioni più significative
Il modello identifica dieci aumenti di due classi e una diminuzione di pari entità:
- TMO: classe 1 → 3; confidenza corrente 36,2%.
- GILD: classe 1 → 3; confidenza corrente 37,2%.
- C: classe 1 → 3; confidenza corrente 33,1%.
- AMGN: classe 1 → 3; confidenza corrente 30,8%.
- DHR: classe 1 → 3; confidenza corrente 34,5%.
- PM: classe 1 → 3; confidenza corrente 29,7%.
- ABT: classe 1 → 3; confidenza corrente 28,7%.
- MS: classe 1 → 3; confidenza corrente 29,1%.
- XOM: classe 1 → 3; confidenza corrente 29,1%.
- LMT: classe 0 → 2; confidenza corrente 31,6%.
- VZ: classe 3 → 1; confidenza corrente 34,0%.
Considerando anche i movimenti di una classe, BA, GE, TJX, VRTX, DE, MRK, SYK, TMUS, GS e SBUX entrano nelle classi 3–4. La composizione del paniere cambia marginalmente: PGR entra nella rilevazione corrente, mentre CVS era presente soltanto in quella precedente; i due titoli non sono inclusi nei confronti individuali.
Indicazioni per la gestione del rischio
Il ritorno di oltre due terzi dei titoli comparabili nelle classi 3–4 suggerisce un aumento della pressione aggregata e una maggiore diffusione del rischio tra i settori. La persistenza della tecnologia nelle fasce elevate si combina ora con una riaccelerazione in Health Care, Industrials e Financials.
Le previsioni possono supportare il monitoraggio del rischio, il dimensionamento delle posizioni e la valutazione delle coperture. Devono essere integrate con liquidità, orizzonte temporale, correlazioni e obiettivi dell’investitore.
Buona settimana
Gandalf Project R&D Team
Avvertenza importante — Non è consulenza finanziaria
Le informazioni contenute nel report sono fornite esclusivamente a scopo educativo e informativo. Non costituiscono una sollecitazione al pubblico risparmio, una raccomandazione di investimento o un’offerta di acquisto o vendita di strumenti finanziari. Gandalf Project non si assume responsabilità per decisioni di investimento prese sulla base del report; gli investitori devono svolgere valutazioni autonome e, se necessario, consultare un consulente finanziario qualificato.
Weekly Volatility Forecast for the S&P 500
The Gandalf Volatility Forecaster points to a sharp reacceleration in forecast volatility. Among the 99 stocks included in both model runs, the share assigned to classes 3–4 rises from 49.5% to 67.7%, reversing the normalisation observed one week earlier.
The analysis is based on a selection of the 100 largest S&P 500 constituents by market capitalisation. The results describe this selected sample rather than the index’s full constituent universe.
The model assigns each stock its most likely volatility class on a scale from 0 to 4: very low, low, normal, high and very high. The percentage displayed in the heatmaps measures relative confidence in the selected classification; it is not the probability of a price increase or decrease.
General context: a return to a more stressed regime
Across the full 100-stock universe, classes 3–4 rise from a combined 49 to 68 constituents. Class 3 increases from 27 to 41 stocks and class 4 from 22 to 27. At the opposite end, class 0 falls from 12 stocks to only one; class 1 declines from 27 to 21 and class 2 from 12 to 10.
The change is therefore not limited to a few extreme cases: the entire distribution shifts towards the upper bands. Within the comparable sample, 19 stocks enter classes 3–4 and only one leaves, pointing to a broad increase in forecast pressure.
| Class | Definition | August 16 | August 23 |
|---|---|---|---|
| 0 | Very low | 12% | 1% |
| 1 | Low | 27% | 21% |
| 2 | Normal | 12% | 10% |
| 3 | High | 27% | 41% |
| 4 | Very high | 22% | 27% |
Distribution of stocks by class
The histogram shows the shift from classes 0–2 towards classes 3–4. Orange represents the previous run and green the current run.
Very low
Low
Normal
High
Very high
Forecast generated on August 16, 2026.
Forecast generated on August 23, 2026.
Sector dynamics
Health Care: the main driver of reacceleration
Health Care includes 15 comparable stocks and records the sharpest sector change. Its average class rises from 1.40 to 2.53 and its share in classes 3–4 from 13.3% to 66.7%. Thermo Fisher Scientific, Gilead, Amgen, Danaher and Abbott move from class 1 to class 3; MRK, Vertex and Stryker enter the high band through one-class moves. The sector therefore shifts from a predominantly low profile to a much more exposed configuration.
Industrials and Financials: pressure increases
Among 11 comparable Industrials, the share in classes 3–4 rises from 36.4% to 63.6% and the average class from 2.00 to 2.73. Boeing, GE and Deere enter class 3, while Lockheed Martin moves from class 0 to class 2. GEV and GLW remain in class 4.
Among 14 comparable Financials, the upper-band share increases from 7.1% to 28.6%. Citigroup and Morgan Stanley move from class 1 to class 3, while Goldman Sachs rises from class 2 to class 3. The sector’s average class increases from 0.86 to 1.71.
Consumer Staples and Energy: upper classes recover
Among six Consumer Staples stocks, the average class rises from 0.83 to 1.83. Philip Morris moves from class 1 to class 3, while the sector’s upper-band share doubles from 16.7% to 33.3%. Among three Energy stocks, the share in classes 3–4 rises from 33.3% to 66.7%, with Exxon Mobil moving from class 1 to class 3.
Technology: elevated volatility persists and strengthens slightly
Information Technology retains the most stressed profile. Among 29 comparable stocks, 96.6% remain in classes 3–4 and the average class rises from 3.69 to 3.79. AMAT, AMD, ANET, APH, AVGO, CRM, CRWD, DELL, GLW, IBM, INTC, KLAC, LRCX, MRVL, MU, NOW, ORCL, PANW, QCOM, SNDK, STX, TXN and WDC concentrate very-high signals.
Consumer Discretionary becomes more stressed; Communication Services remains stable
Among eight comparable Consumer Discretionary stocks, the share in classes 3–4 rises from 62.5% to 87.5%, supported by the entries of TJX and Starbucks. Across Communication Services, the share remains at 75.0%: Verizon moves from class 3 to class 1, while T-Mobile enters class 3.
Most significant changes
The model identifies ten two-class increases and one decrease of the same magnitude:
- TMO: class 1 → 3; current confidence 36.2%.
- GILD: class 1 → 3; current confidence 37.2%.
- C: class 1 → 3; current confidence 33.1%.
- AMGN: class 1 → 3; current confidence 30.8%.
- DHR: class 1 → 3; current confidence 34.5%.
- PM: class 1 → 3; current confidence 29.7%.
- ABT: class 1 → 3; current confidence 28.7%.
- MS: class 1 → 3; current confidence 29.1%.
- XOM: class 1 → 3; current confidence 29.1%.
- LMT: class 0 → 2; current confidence 31.6%.
- VZ: class 3 → 1; current confidence 34.0%.
When one-class moves are included, BA, GE, TJX, VRTX, DE, MRK, SYK, TMUS, GS and SBUX enter classes 3–4. The universe composition changes marginally: PGR enters the current run, while CVS appeared only in the previous one; neither stock is included in individual week-over-week comparisons.
Risk-management implications
The return of more than two-thirds of comparable stocks to classes 3–4 suggests higher aggregate pressure and a broader distribution of risk across sectors. Technology’s persistent upper-band profile is now combined with reacceleration across Health Care, Industrials and Financials.
The forecasts may support risk monitoring, position-sizing reviews and hedging assessments. They should be considered together with liquidity, investment horizon, correlations and the investor’s objectives.
Have a good week
Gandalf Project R&D Team
Important notice — Not financial advice
The information contained in this report is provided solely for educational and informational purposes. It does not constitute a solicitation of public savings, an investment recommendation, or an offer to buy or sell financial instruments. Gandalf Project accepts no responsibility for investment decisions made on the basis of this report. Investors should conduct their own assessments and, where appropriate, consult a qualified financial adviser.
